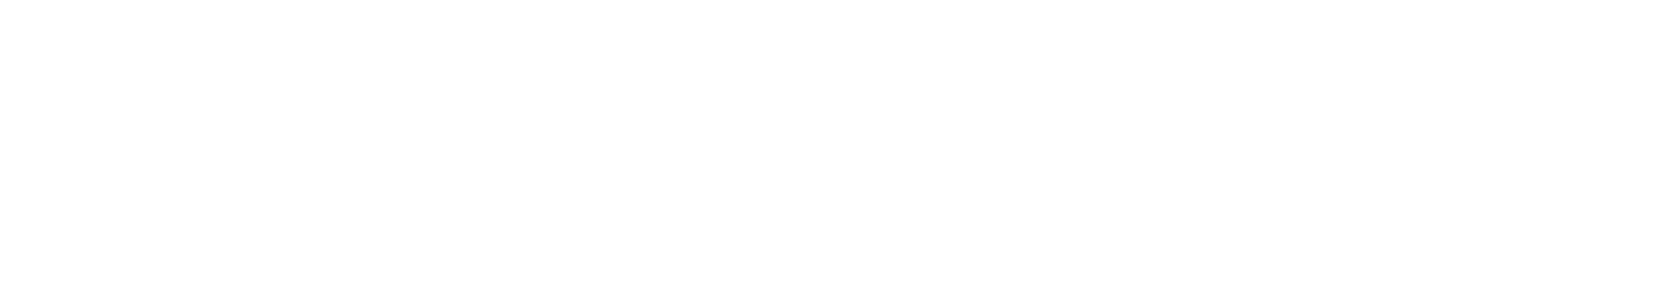

The International Transition Plan Network’s (ITPN) interactive global map is a central resource tracking where transition plan rules, regulations and guidance are in place and emerging.
The map highlights three categories of jurisdictions:
Mandatory transition plan rules, regulations or guidance in place
Mandatory transition plan rules, regulation or guidance in progress
Voluntary transition plan guidance in place
It reflects two main pathways: adoption of ISSB Standards (IFRS S1 & S2) and jurisdiction-specific guidance or rules.
This blog serves as the central home for all historic updates to the map. With each quarter bringing substantive updates, this article will highlight the latest developments so readers can follow how the global landscape evolves over time. The next map update is due in late 2026.
Q3 2026 – Key developments:
Reflecting progress between July and September 2026, we have updated seven jurisdiction profiles and added two new jurisdictions: Honduras and Oman.
Updated profiles
- Australia: Treasury released voluntary transition planning guidance on 24 August 2026. It builds on the Transition Plan Taskforce’s Transition Planning Cycle and explains how transition planning interacts with disclosure under AASB S2.
- Brazil: Brazil’s Central Bank updated the GRSAC Report disclosure standard through BCB Resolution 586 on 3 September 2026, as part of its strategic agenda. From January 2027, regulated financial institutions must disclose transition plans where they have one, with required content set out in Table PTC1.
- EU: The European Commission adopted revised ESRS and a voluntary standard for smaller companies on 3 July 2026. EFRAG published draft standards for non-EU companies (ESRS-40a) on 23 July 2026, with consultation open until 31 October 2026.
- New Zealand: The XRB consulted on a draft climate reporting roadmap from 23 July to 30 September 2026. It proposes a new IFRS S2-based standard, mandatory from 1 January 2028, with at least limited assurance from 1 January 2033.
- Philippines: The SEC formally approved the adoption of IFRS S1 and S2 as PFRS S1 and S2 on 14 July 2026, with tiered implementation from 1 January 2026 to 1 January 2028.
- Singapore: ACRA launched a consultation on 27 July 2026 on draft Singapore Sustainability Disclosure Standards based on the ISSB standards, with only SFRS S2 proposed as mandatory. The consultation closes on 25 October 2026.
- South Africa: The National Treasury has launched a public consultation setting out proposals for a Climate Transition Planning and Disclosure Framework for financial institutions in South Africa, closing on 10 December 2026.
- South Korea: The FSC finalised its mandatory ISSB-based disclosure roadmap for large KOSPI-listed companies on 8 July 2026. Companies with assets of at least KRW10 trillion report from 2028 for fiscal year 2027, with the threshold lowering from 2029.
- UK: The FCA published PS26/19 on 30 September 2026, replacing TCFD-aligned requirements for listed issuers with UK SRS-aligned requirements on a comply-or-explain basis, for periods beginning on or after 1 January 2027. Companies must state whether they have published a transition plan and where to find it, or why not. The FCA is consulting until 28 October 2026 on a Technical Note on proportionate application.
New jurisdictions
- Honduras: IFRS S1 and S2 (NIIF S1 and S2) were adopted through Resolución JTNCA 006-01/2025 on 3 May 2025. They apply to taxpayers classed as ‘grandes contribuyentes’ at the end of FY2026, CNBS-regulated entities and entities required to report publicly under IFRS, with application effective before the start of FY2028. There is currently no mandatory assurance regime.
- Oman: The Financial Services Authority adopted IFRS S1 and S2 through Decision No. E/7/2026 on 17 March 2026, for listed public joint-stock companies and financial institutions. Application is mandatory from 1 January 2029, with Scope 3 disclosures from 1 January 2030.

Q2 2026 – Key developments:
New jurisdictions added to the map:
- Peru’s Technical National Council of Accounting (CNC) approved mandatory application of IFRS S1 and S2 in March 2026, coming into force on 1 January 2029 for regulated companies and larger non-regulated entities.
- Ethiopia’s Accounting and Auditing Board (AABE) published a consultation on a draft four-stage ISSB adoption roadmap in February 2026, with large companies proposed to begin reporting from FY2026 or FY2027.
- Uzbekistan adopted IFRS S1 and S2 by Presidential Decree (No. PP-282, September 2025), mandatory for public interest entities from 1 January 2027.
- Kyrgyzstan has been confirmed by the IFRS Foundation as a jurisdiction that has announced plans to incorporate ISSB Standards, with details yet to be finalised.
Updates to existing profiles:
- Japan’s FSA finalised a Cabinet Office Order in February 2026 making SSBJ Standards mandatory for TSE Prime Market companies, phased from FY ending March 2027. Japan’s GX Emissions Trading System launched in April 2026, with covered companies (300-400 companies; 60% of Japan’s emissions) required to publish and submit emissions reduction pla[JM3.1]ns. A new GX Future Consortium will provide guidance on transition plan disclosure.
- Singapore’s MAS finalised transition planning guidelines for all MAS-regulated financial institutions in March 2026, covering banks, insurers and asset managers, coming into force in September 2027.
- Hong Kong SAR’s large cap issuers are now subject to mandatory IFRS S2-aligned transition plan disclosure requirements from 1 January 2026. Hong Kong’s Green and Sustainable Finance Cross-Agency Steering Group launched a Transition Plan Disclosure Pilot in January 2026.
- South Korea’s KSSB published final sustainability disclosure standards (KSSB 1 and KSSB 2) aligned with IFRS S1 and S2 in February 2026. A mandatory implementation roadmap consultation closed in March 2026.
- Zimbabwe’s PAAB published a consultation on a draft ISSB adoption roadmap in early 2026, proposing phased implementation beginning 1 January 2026 for the largest entities.
- The UK Government published the final UK Sustainability Reporting Standards in February 2026, mandatory for listed companies from January 2027. Confirmation of the government’s transition plan policy is still outstanding, following the close of the consultation in September.
- The EU Omnibus I Directive entered into force in March 2026, narrowing CSRD scope, postponing requirements to 2027, and removing the mandatory transition plan development requirement from CSDDD. The requirement to disclose a transition plan (if the entity has one) is retained under CSRD.
- New Zealand’s existing TCFD-aligned mandatory framework (in force since 2023) has been updated to reflect NZ XRB’s ongoing ISSB harmonisation work and expanded transition planning guidance suite.
- Brazil’s CVM amended its sustainability disclosure framework on 29 May 2026, shifting from planned mandatory requirements to a voluntary “comply-or-explain” system for listed companies. Companies that opt in must report in line with Brazilian standards aligned with IFRS S1 and S2, obtain reasonable assurance, and commit to at least three consecutive years of reporting; those that do not report must publicly explain their decision. Mandatory requirements via the National Monetary Council remain in place for financial institutions from 2026/2028.
March 2026 – Key developments:
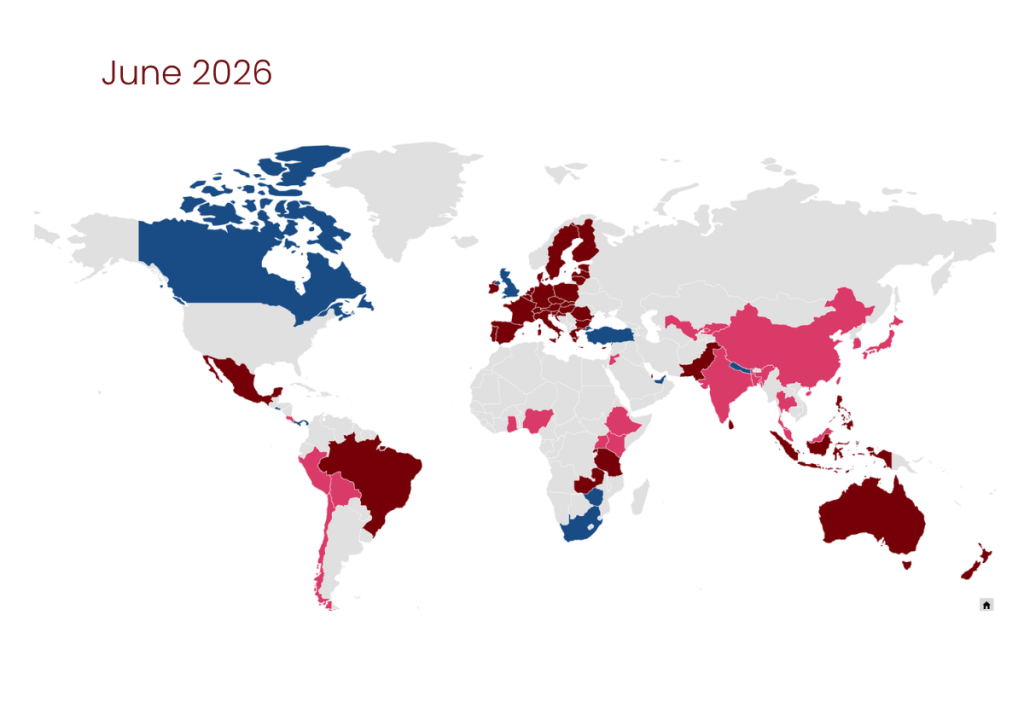
- In March 2026 the Monetary Authority of Singapore (MAS) finalised its Guidelines on Environmental Risk Management – Transition Planning, introducing supervisory transition planning guidelines for all MAS‑regulated financial institutions. The guidelines, issued as three documents, separately set out MAS’ supervisory expectations for banks, insurers and asset managers “to manage the transition and physical risks they face from climate change as part of a sound transition planning process”. The guidelines come into force in September 2027.
February 2026 – Key developments:
- Reporting requirements aligned with IFRS S2 are now in force in four new jurisdictions as of 1 January 2026: Brazil, Hong Kong, the Philippines, and Qatar.
- The Brazilian Central Bank and the UK Financial Conduct Authority have both published consultations which include transition plan‑related requirements.
- China published new ISSB‑aligned draft climate‑related disclosures in December.
- Hong Kong’s Green and Sustainable Finance Cross‑Agency Steering Group announced a Transition Plan Disclosure Pilot as part of its 2026–2028 Strategic Priorities, designed to strengthen Hong Kong’s sustainable finance and disclosure ecosystem.
- Transition plan requirements for EU credit institutions came into force on 11 January under the Capital Requirements Directive (CRD IV). Guidelines by the European Banking Authority require credit institutions to develop and monitor transition plans as part of their ESG risk management framework.
- The European Central Bank has included assessing banks’ prudential transition plans as part of its new supervisory priorities.
- The EU Omnibus outcome was confirmed last year – transition plans were retained within the Corporate Sustainability Reporting Directive, and removed from the Corporate Sustainability Due Diligence Directive.
October 2025 – Initial map launch:
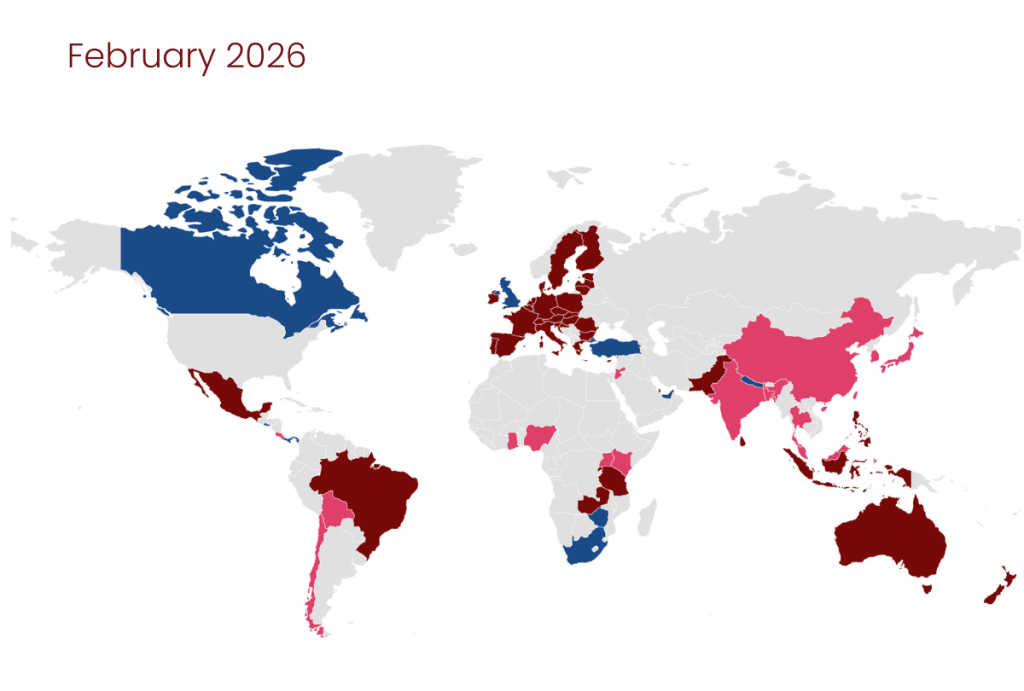
- Acceleration toward mandatory: Countries including Australia, Mexico, New Zealand, Singapore and Türkiye already require transition plan disclosure.
- Upcoming requirements: Bangladesh, Brazil, Canada, China, Hong Kong, South Korea, and the UK, among others, are advancing new mandatory rules.
- Convergence around ISSB: 37 jurisdictions are working towards or aligning with ISSB Standards.
- Looking ahead: In the next three years, mandatory disclosure will come into force in over half of the G20.